|
OPERATOR SIGNAL
|
|
BEFORE THE INVESTMENT COMMITTEE
|
Volume. Collections. Margin.
This week, Operator Signal looks at a Healthcare150 survey showing that hospital investors are watching operating margin more closely than headline volume, a diligence framework for testing whether patient activity converts into collectible revenue, and Prospect Medical Holdings as a reminder that liquidity structures cannot compensate for weak operating cash generation.
|
|
Hi there,
Across all three topics, the message is consistent: healthcare operators can show demand and still disappoint investors if revenue leakage, payer mix, cost growth, or balance sheet structure prevents that demand from reaching earnings.
The best healthcare assets will not just prove utilization. They will prove conversion from volume to cash to margin.
Exact Insight helps investors test the commercial facts before the deal closes. Learn more: https://www.exactinsight.ai/
Exact Insight surfaces these patterns early, directly from operator conversations, before they show up in CIMs or IC memos.
Access the full briefing or request expert calls in this sector to go deeper.
|
|
|
|
INSIGHTS FROM THE NETWORK
Hospital Investors Are Watching Conversion, Not Just Volume
In the survey we conducted in partnership with Healthcare150, 133 respondents identified the hospital KPIs they expect to watch most closely in H2 2026. Operating margin ranked first at 29%, followed closely by bad debt at 26%. Admissions and outpatient volumes each received 23%.
The narrow spread matters. Investors are not treating hospital performance as a single growth metric. They are asking whether patient activity can move through the revenue cycle, survive collection friction, and ultimately support profitability. Volume still matters, but it is no longer enough on its own.
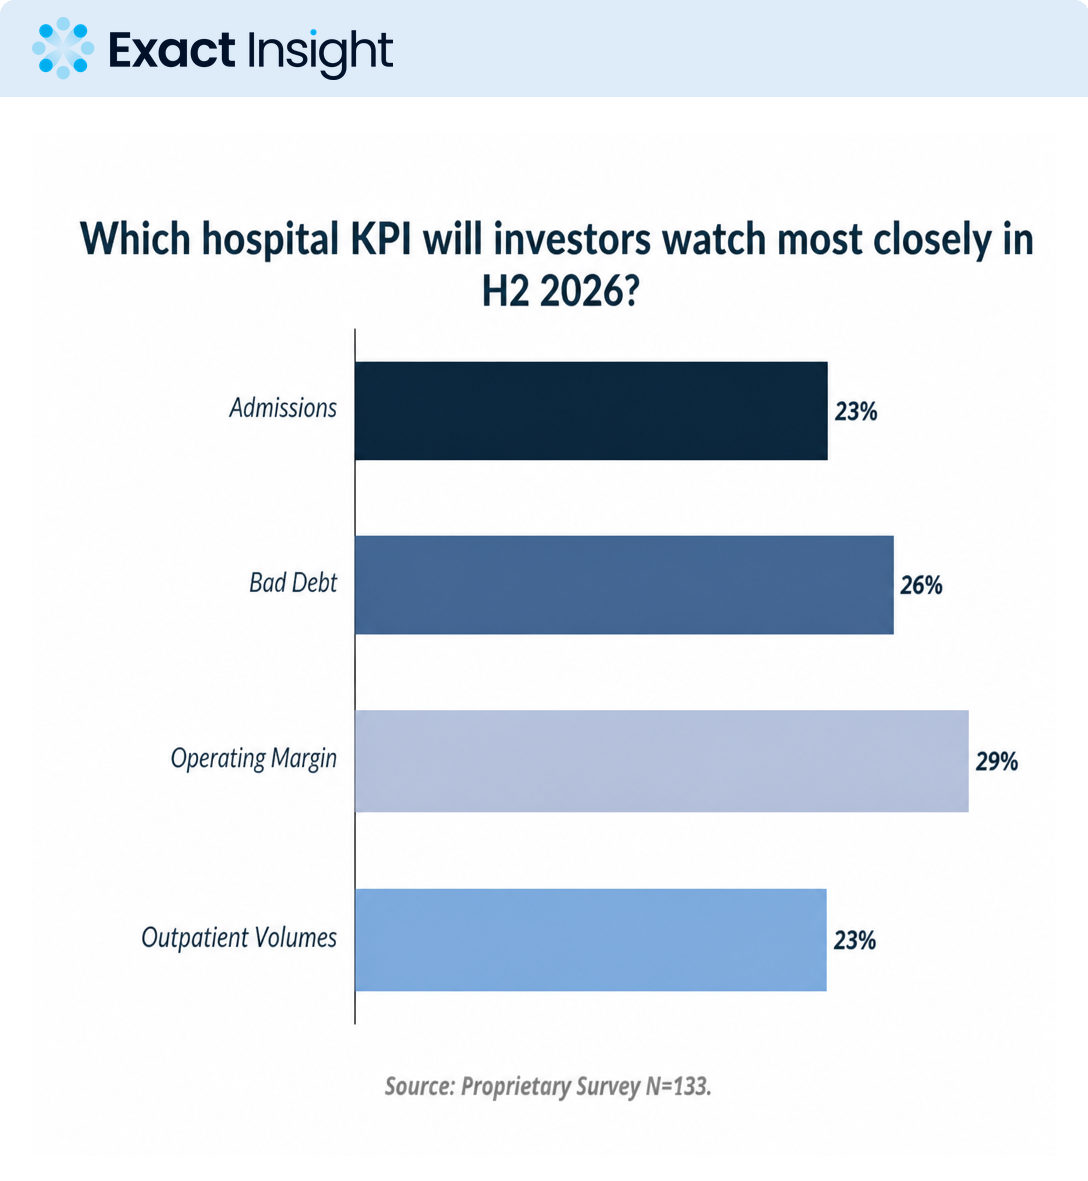
For healthcare investors, that shifts the diligence lens. A hospital platform with rising utilization may still be fragile if payer mix is deteriorating, denials are increasing, labor costs are absorbing incremental revenue, or bad debt is climbing faster than gross charges. The more useful screen is whether management can connect demand, collections, and margin in one operating model.
|
|
|
|
PRE-DEAL INTELLIGENCE
Can Volume Survive the Revenue-Cycle Stress Test?
Hospital diligence should not treat patient demand as revenue. The stronger test is to follow the same encounter from scheduling and authorization through coding, denial management, patient responsibility, cash collection, labor intensity, and margin capture. A platform can show rising utilization and still weaken economically if the revenue-cycle bridge leaks faster than volume grows.
A buyer should pressure-test four layers before underwriting growth. First, service-line conversion: which procedures turn encounters into collectible net revenue after payer mix, denials, charity care, and underpayment? Second, collection durability: how much bad debt is caused by controllable front-end execution versus patient affordability pressure? Third, margin absorption: does incremental volume require nurses, rooms, outsourced labor, or capex that consumes the revenue? Fourth, operating visibility: can leadership see leakage by site and service line quickly enough to fix it before it becomes normalized performance.
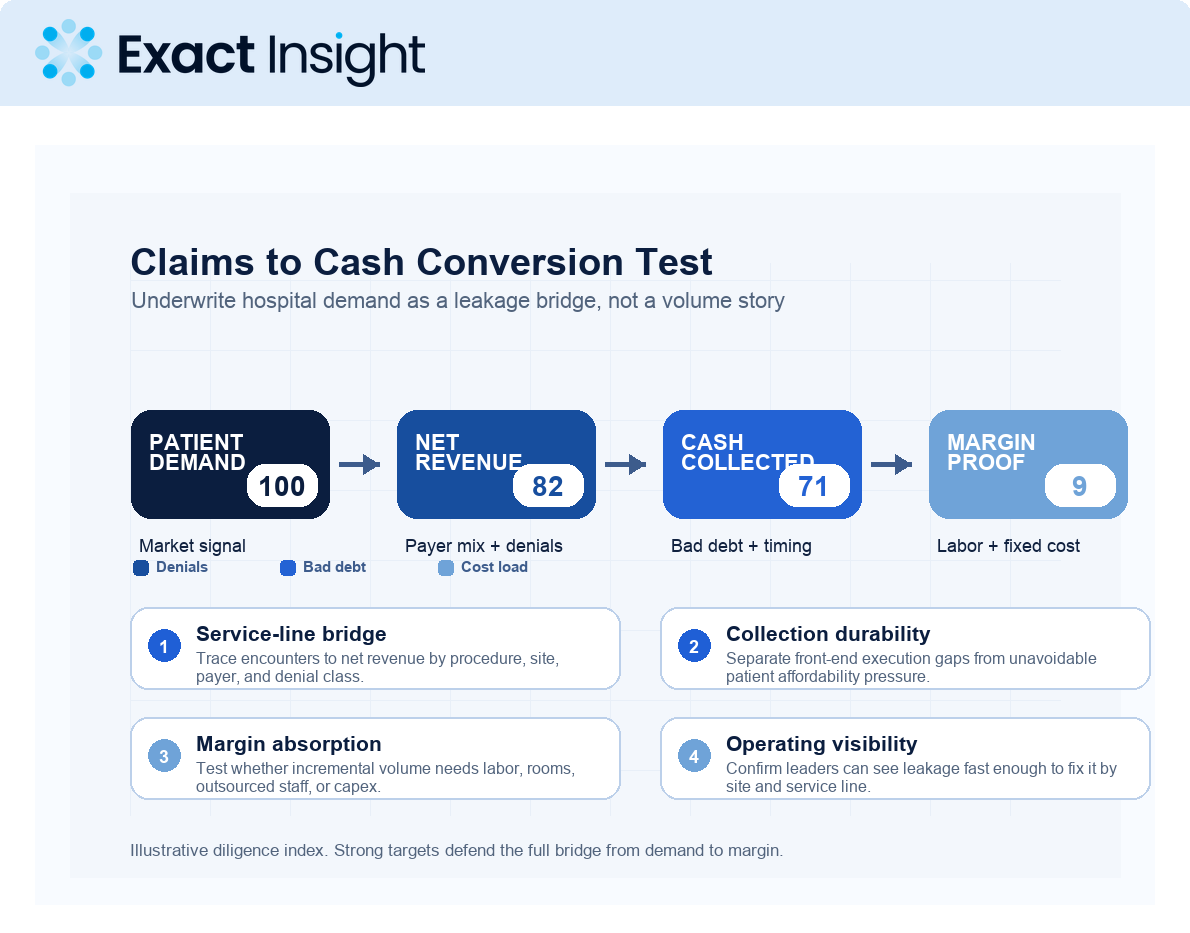
The underwriting bar is not "more visits." It is a claims-to-cash bridge that finance, operators, and revenue-cycle leaders can defend together. If that bridge is weak, growth can make the hospital look bigger while making the equity story less bankable.
|
|
|
|
LESSONS FROM THE FIELD
Prospect Medical Shows Why Liquidity Engineering Cannot Replace Cash Flow
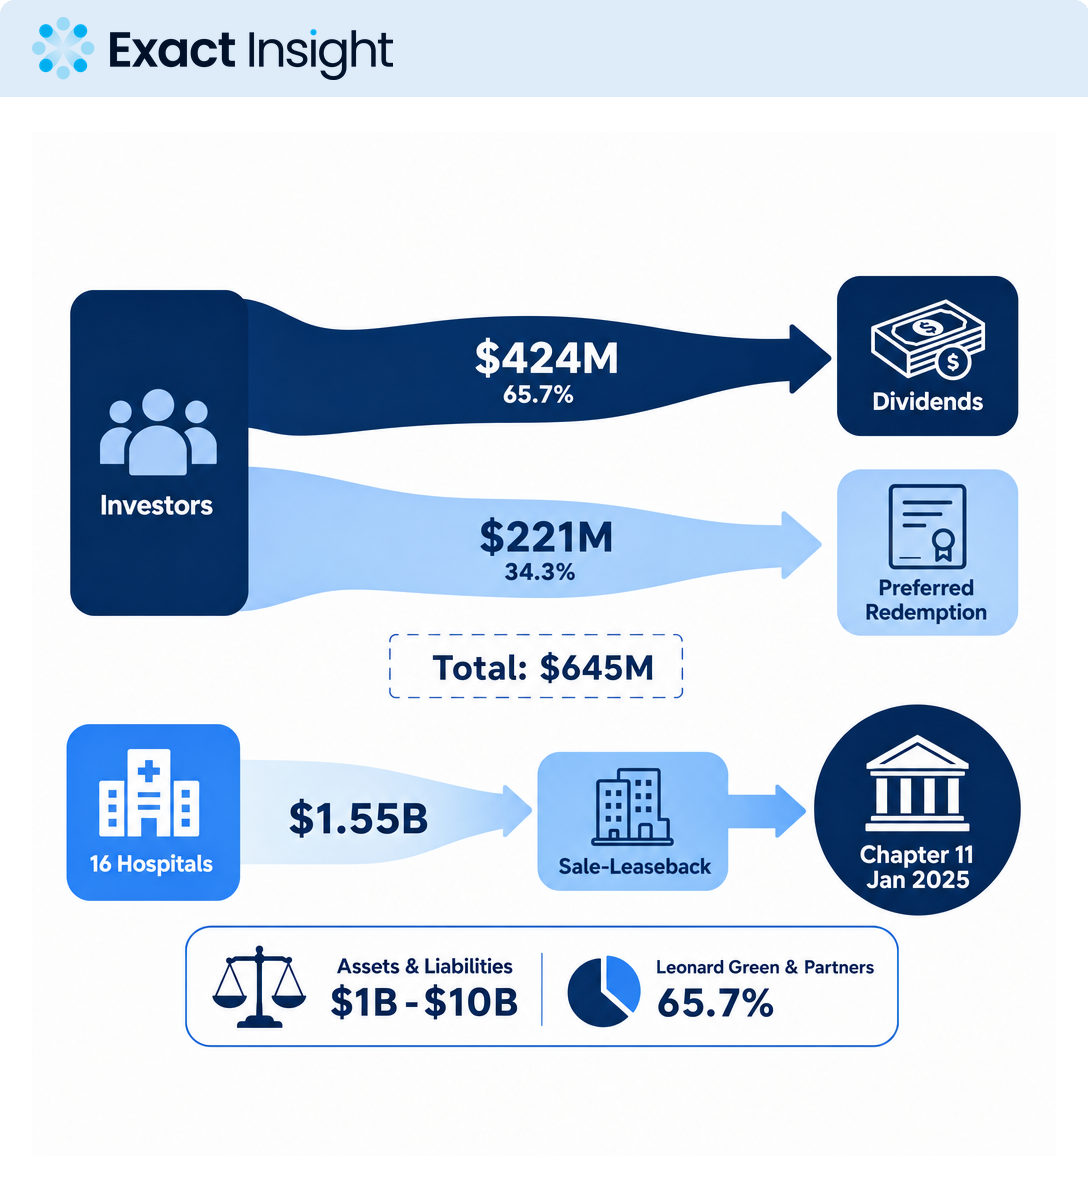
Prospect Medical Holdings filed for Chapter 11 bankruptcy in January 2025 after years of financial stress. HealthLeaders reported that the system listed between $1 billion and $10 billion in assets and liabilities, operated 16 hospitals, and had struggled to divest facilities while managing debt, lease obligations, and operational pressure. The same report cited a Senate Budget Committee finding that Leonard Green & Partners collected $424 million of the $645 million in dividends and preferred stock redemption paid to investors while Prospect used a $1.55 billion sale-leaseback with Medical Properties Trust.
| |
The diligence lesson is direct: balance sheet maneuvers can create liquidity, but they do not prove that a hospital business can generate durable operating cash flow. When rent obligations, debt service, payer pressure, and underinvestment collide, financial engineering can narrow the room for operational recovery. For buyers, hospital underwriting has to test whether cash conversion can sustain the asset after the transaction structure is removed from the story.
|
|
|
|
|
INTERESTING ARTICLES
Worth Your Time
Hospital margin trends in 2026 show rising cost pressure
Hospital margins drop to 1.4% as bad debt, charity care soar
Hospital point-of-care collections rise, but bad debt persists
|
|
Operator Signal · by Exact Insight
Exact Insight · 170 Mason Street, Greenwich, Connecticut 06830, United States
You're receiving this because you subscribed to Operator Signal.
|
|